What is the scope and industry significance of the Hot-Rolled Steel Coil Market?
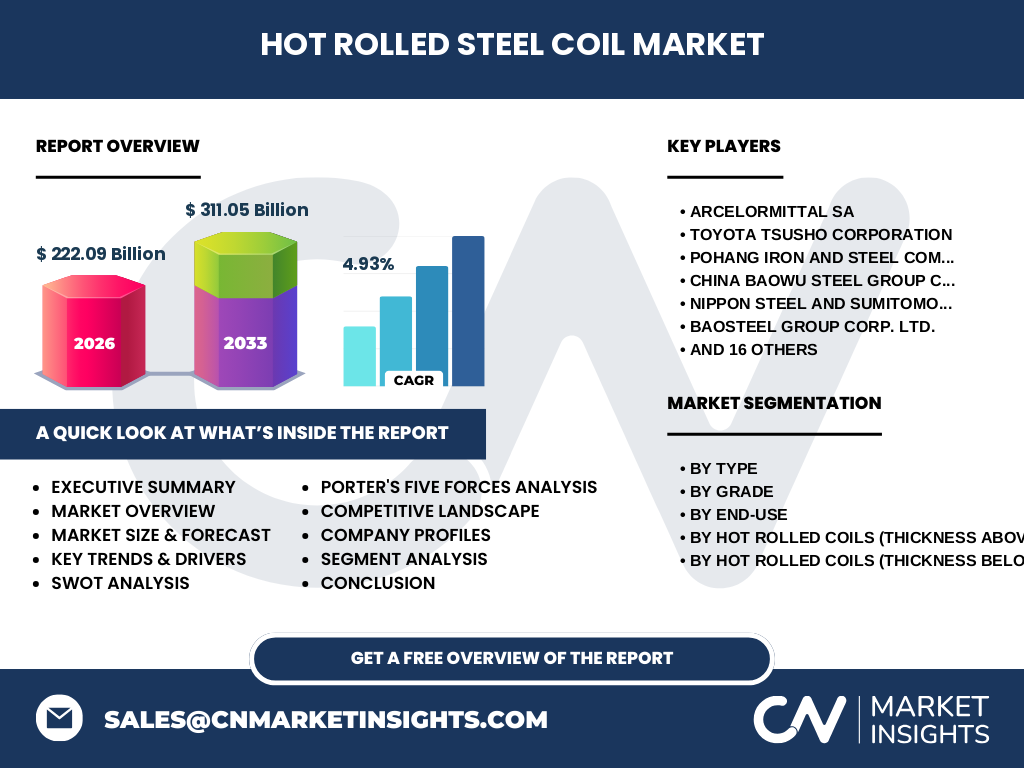
The Hot-Rolled Steel Coil Market represents a foundational pillar of heavy manufacturing, valued at $222.09 Billion in 2026. This foundational sector supplies essential raw materials processed via continuous casting and hot strip mills, feeding directly into structural beams, automotive chassis, and large-diameter energy pipelines.
Structural Growth Drivers and Market Restraints
Our analysis indicates that rapid urbanization and massive infrastructure investments are primary growth drivers, countered by stringent environmental regulations from bodies like the EPA and EU ETS. Volatility in raw material coking coal and iron ore prices remains a key restraint challenging operating margins across global facilities.
Emerging Trends and Growth Patterns
The industry is witnessing an accelerated shift toward green steel production utilizing electric arc furnaces (EAF) and hydrogen-based reduction. Industry leaders like ArcelorMittal SA and ThyssenKrupp AG are pioneering ultra-low carbon hot-rolled coils to satisfy strict Scope 3 emission mandates demanded by downstream automotive buyers.
How did COVID-19 impact the Hot-Rolled Steel Coil Market recovery trajectory?
The pandemic caused severe supply chain fractures and sudden mill shutdowns in 2020, followed by an aggressive post-lockdown rebound. Pent-up demand from construction and automotive sectors triggered historic price surges, forcing buyers to diversify sourcing from regional hubs near major ports like Antwerp and Shanghai.
Competitive Benchmarking and Market Concentration
The landscape features high concentration among state-backed giants like China Baowu Steel Group Corp. and multinational powerhouses like Nippon Steel And Sumitomo Metal Corporation (NSSMC). Strategic consolidation and technological partnerships in advanced high-strength steels define how top players maintain pricing power and defend their market share.
Executive Summary: Hot-Rolled Steel Coil Market Outlook
Our comprehensive research projects the Hot-Rolled Steel Coil Market to expand from $222.09 Billion in 2026 to $311.05 Billion by 2033, exhibiting a robust CAGR of 4.93%. This trajectory underscores the critical role of lightweighting trends and energy infrastructure expansion in driving long-term volume demand.
Market Forecast Analysis (2027 to 2033)
Driven by emerging market industrialization and green energy projects, the sector is set for steady upward momentum, scaling to $311.05 Billion by 2033 at a 4.93% CAGR. Investors should note that decarbonization CapEx will separate high-margin producers from legacy blast-furnace operators during this forecast window.
Comprehensive Segmentation Analysis
Market segmentation spans thickness categories like Hot Rolled Coils (Thickness Above 3 Mm) and Hot Rolled Coils (Thickness Below 3 Mm), alongside grades ranging from Low-Carbon Steel to Alloy Steel. End-use verticals encompass Construction And Infrastructure, Automotive, and Oil And Gas Or Energy, dictating specialized metallurgical requirements.
Regional Market Performance and Geographic Distribution
Asia-Pacific dominates consumption, powered by intense construction activity in China and India, while North America and Europe focus on high-value automotive grade coils. Regional performance directly correlates with local environmental compliance costs and the proximity of integrated steel mills to major maritime logistics corridors.
In-Depth Regional Review
Asian markets benefit from localized raw material supply chains and massive state-backed industrial parks, whereas European producers face intense pressure from the Carbon Border Adjustment Mechanism (CBAM). Meanwhile, North American mills maintain steady pricing protected by Section 232 tariffs and robust regional energy exploration.
Strategic Positioning of Leading Companies
Key market participants such as Tata Steel Ltd., Hyundai Steel Co., and United States Steel Corporation leverage localized production footprints to mitigate trade friction. Their strategic focus heavily prioritizes value-added automotive and pressure vessel grades over commoditized structural coils.
Porter's Five Forces Analysis
Rivalry is intense due to high fixed operating costs and global overcapacity, while supplier power remains moderate given consolidated iron ore mining. Buyer power is elevated among major automotive OEMs, whereas the threat of substitution from advanced aluminum and carbon composites remains a persistent medium-term risk.
SWOT Analysis of the Industry
Strengths include unmatched material strength and cost efficiency, while weaknesses involve high carbon intensity and water usage. Opportunities abound in renewable energy wind tower plates, whereas threats stem from geopolitical trade disputes, carbon taxation, and fluctuating scrap metal availability.
Value Chain Analysis
The value flow initiates with upstream mining of iron ore and coking coal, moving through sinter plants, blast furnaces, and hot strip rolling mills. Midstream service centers process coils via pickling and slitting before delivery to downstream fabricators in the Shipbuilding And Marine and Industrial Equipment sectors.
Investment Insights and High-Potential Areas
High-potential investment pockets center on hydrogen-ready direct reduced iron (DRI) plants and advanced high-strength low alloy (HSLA) coil production lines. Backing mills equipped with waste-heat recovery systems offers superior risk-adjusted returns amidst tightening global emissions regulations.
Conclusion and Strategic Takeaways
The Hot-Rolled Steel Coil Market is undergoing a structural green transition while expanding toward a projected $311.05 Billion valuation by 2033. Success in this landscape hinges on proactive decarbonization, technological agility, and strategic alignment with high-growth automotive and renewable energy end-use sectors.
Research Methodology
Our analytical framework triangulates bottom-up mill production data with top-down macroeconomic indices, cross-verified through primary interviews with C-suite executives at firms like Jindal South West Steel Ltd. and Gerdau S.A. Trade registry statistics and customs data from major ports ensure high fidelity in our sizing baselines.
Scope of the Report
This report evaluates the global Hot-Rolled Steel Coil Market industry trends across key geographic regions, material grades, and end-use verticals from 2026 through 2033. Excluded from this scope are cold-rolled downstream processing and non-ferrous metal coil markets, maintaining a strict focus on hot-rolled carbon and alloy steel products.
Recent Industry Developments and Strategic Moves
Recent milestones include Novolipetsk Metallurgical Combine Group and Ansteel Group commissioning advanced EAF units to lower carbon footprints. Meanwhile, strategic joint ventures between Jindal Stainless Hisar Limited and regional fabricators highlight a surging industry-wide push toward specialized value-added coil offerings.